 By
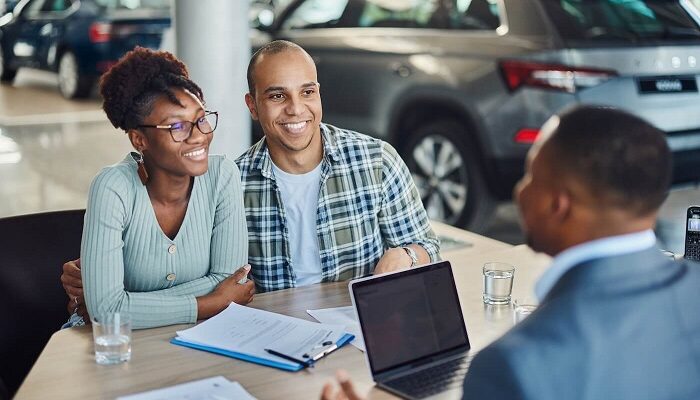
Sitting in a car dealership finance office can feel like a test of endurance. You settle on a vehicle, negotiate terms, and sign preliminary paperwork so the finance manager can secure an interest rate. A few days later, your phone buzzes with a barrage of alerts from your credit monitoring apps. Where you expected a single credit check, you find eight, ten, or even fifteen distinct hard inquiries stamped across your credit profiles.
This practice is widespread across the auto retail industry, and the initial wave of notifications often triggers panic. While the sudden appearance of ten hard inquiries looks alarming on paper, understanding how credit scoring models process automotive financing helps separate cosmetic clutter from actual financial damage. With the right steps, you can assess the real impact, clean up unauthorized pulls, and shield your credit profile from long-term harm.
Why Dealerships Blast Your Credit to Multiple Lenders
The sudden multiplication of inquiries comes from a common dealership tactic known as credit shotgunning. Dealership finance departments rarely lend their own money. Instead, they act as brokers between car buyers and a network of lenders, including automaker captive finance arms, national banks, regional credit unions, and subprime lending institutions.
When you hand over your signed credit application, the finance manager rarely submits it to a single institution to wait patiently for a response. Instead, they upload your details into centralized automotive loan portals like DealerTrack or RouteOne and blast the application out to five, ten, or more prospective lenders simultaneously.
Finance managers do this for two reasons: speed and profit. Blasting the application yields rapid approvals, allowing the dealership to close the sale before you walk off the lot. More importantly, it creates competition among lenders, allowing the dealership to identify which institution offers the most advantageous dealer reserve. The dealer reserve is an interest rate markup that the financing institution shares with the dealership as commission. While this process benefits the dealership’s bottom line, it frequently leaves buyers feeling blindsided by the resulting footprint on their credit reports.
How Multiple Auto Inquiries Actually Affect Your Score
The good news is that the cosmetic damage on your credit report rarely matches the mathematical penalty applied to your credit score. Modern credit scoring algorithms recognize that consumers shopping for big-ticket installment loans need to compare rates without destroying their credit standing.
Both FICO and VantageScore feature built-in deduplication mechanisms designed specifically for auto loans, mortgages, and student loans. Under these models, multiple inquiries generated within a dedicated shopping window are condensed into a single scoring event.
Depending on the specific FICO scoring version a lender reviews, this rate-shopping window spans between 14 and 45 days. Older FICO models utilize a 14-day window, while newer iterations grant up to 45 days. VantageScore models consolidate auto financing inquiries made within a rolling 14-day window. Under these rules, whether the dealership pinged five banks or fifteen banks, the scoring calculation assesses the same penalty as if your credit had been checked only once.
FICO models also incorporate a 30-day buffer period. Any auto loan inquiries that occurred within the trailing 30 days are completely ignored by the algorithm. Once that 30-day cushion passes, all qualified auto inquiries falling within your shopping window are bundled into one penalty, typically costing a modest three to five points.
When Dealership Inquiries Cause Legitimate Financial Harm
While the scoring deduplication rule protects your baseline points, credit shotgunning is not entirely harmless. Several scenarios exist where multiple inquiries cause tangible difficulties:
Miscoded Inquiries
The deduplication algorithm relies on the lender correctly reporting the inquiry as an automotive loan inquiry. If an aggressive finance manager sends your file to alternative financing companies or unsecured loan platforms, those pulls may be categorized as personal loans or revolving credit checks. When that happens, the system treats each inquiry individually, triggering compounding point deductions that can knock significant points off your score.
Manual Underwriting Scrutiny
Algorithmic scores are only half the battle. If you plan to apply for a mortgage, a business loan, or a premier credit card shortly after buying a car, a human underwriter will examine your full credit report. Even if your score bounced back, a long string of recent hard inquiries can raise red flags. Underwriters may assume you were desperate for financing, struggling to gain approval, or carrying undisclosed debt obligations that have not yet appeared on your balance sheet.
Inquiries Made Without Permissible Purpose
Under the Fair Credit Reporting Act, a business must have a permissible purpose and legitimate authorization before accessing your consumer report. Some dealerships pull credit before a consumer has even agreed to look at numbers, sometimes claiming a credit run was necessary just to test drive a vehicle or verify identity. A pull performed without written or verifiable verbal consent is a violation of federal credit reporting laws.
Steps to Clean Up and Contest Hard Inquiry Damage
If your credit profile took an unfair hit from dealership shotgunning, taking structured corrective action will restore your report.
Audit All Three Bureau Disclosures
Do not rely solely on summary dashboards from free monitoring apps. Access your complete credit reports from Equifax, Experian, and TransUnion. Dealerships rarely pull all three bureaus equally; they often target whichever bureau displays your strongest local score. Identify every financial institution that pulled your file, note the exact date of each inquiry, and verify how the inquiry was categorized.
Challenge Inquiries Run Without Written Authorization
If the dealership pulled your credit before you signed a financing authorization, contact the dealership immediately. Ask to speak directly with the General Manager or the Finance Director. Explain calmly that unauthorized hard inquiries were initiated on your profile without an executed credit application.
Request that the dealership issue a formal inquiry removal letter to the affected credit bureaus confirming the inquiries were initiated in error. Reputable dealerships will cooperate to avoid regulatory complaints or statutory penalties under consumer protection statutes.
File Targeted Disputes with Credit Reporting Agencies
For inquiries originating from banks or lenders you never authorized the dealer to contact, you have the right to file formal disputes directly with the credit bureaus. You can submit disputes online or send a formal letter via certified mail.
Specify that the inquiries in question were submitted without your informed consent, that no relationship was established with the listed institutions, and that the inquiries must be removed due to a lack of permissible purpose. Never dispute an inquiry associated with the specific lender that ultimately financed the vehicle you purchased, as disputing the inquiry for an active, funded account can complicate the reporting of your positive payment history.
Request Direct Rescissions from Non-Funding Lenders
If a dispute through the bureau stalls, reach out directly to the compliance or credit reporting departments of the individual lenders that declined your application or failed to fund the deal. Send a concise request asking them to delete their hard pull as a courtesy, stating that the dealership routed the application without your express direction. Many banks routinely grant deletion requests for applications that did not result in an open account.
Protecting Your Credit on Future Vehicle Purchases
The most effective way to handle dealership credit damage is to eliminate the opportunity before it arises.
Before stepping onto a dealer lot, secure a pre-approval from your own bank or a local credit union. Walking into the showroom with financing already arranged removes the dealership finance department from the equation entirely. If you use outside financing, inform the salesperson in writing that you are an outside-financed or cash buyer and do not authorize any credit checks.
If you must utilize dealer financing, require clear boundaries. Write on your paperwork that you authorize submissions only to the vehicle manufacturer’s captive lender and no more than two specific partner banks. Taking control of the financing workflow ensures you drive home in your new vehicle with your credit score and peace of mind intact.




Comments